


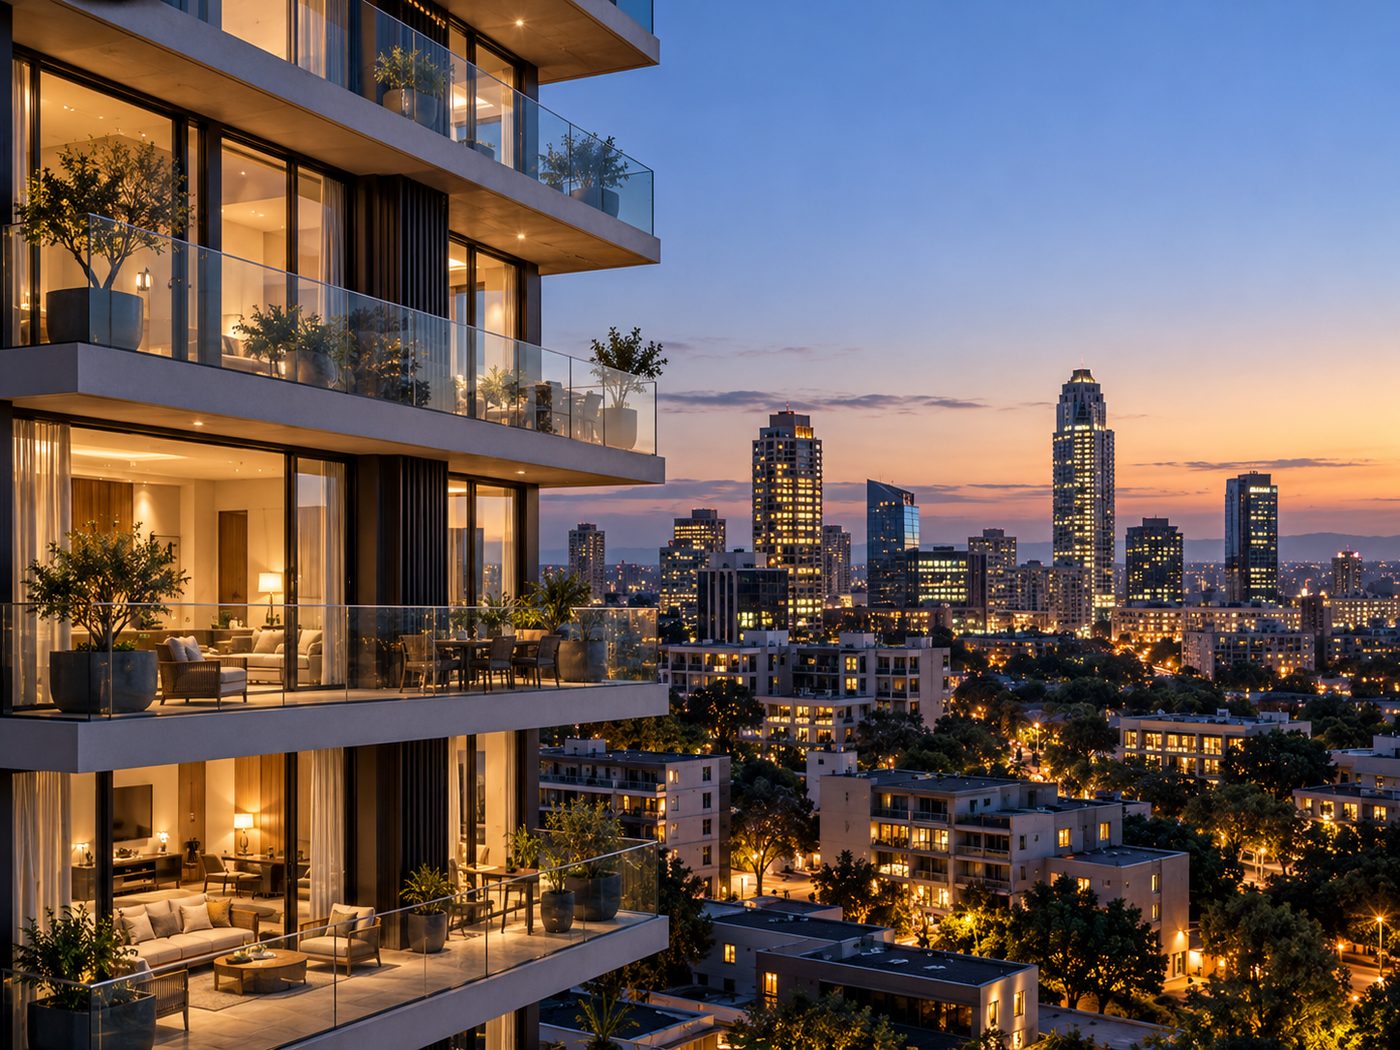
 ApartmentAvailable Now
R19 500/mo
2 Bedroom Apartment near Sandton City
Sandton
Brackenhurst · Brackendowns · Sandton
Rental homes in Brackenhurst, Brackendowns and Sandton, looked after closely.
Available now
Homes we are letting now. We look after each one ourselves.
ApartmentAvailable Now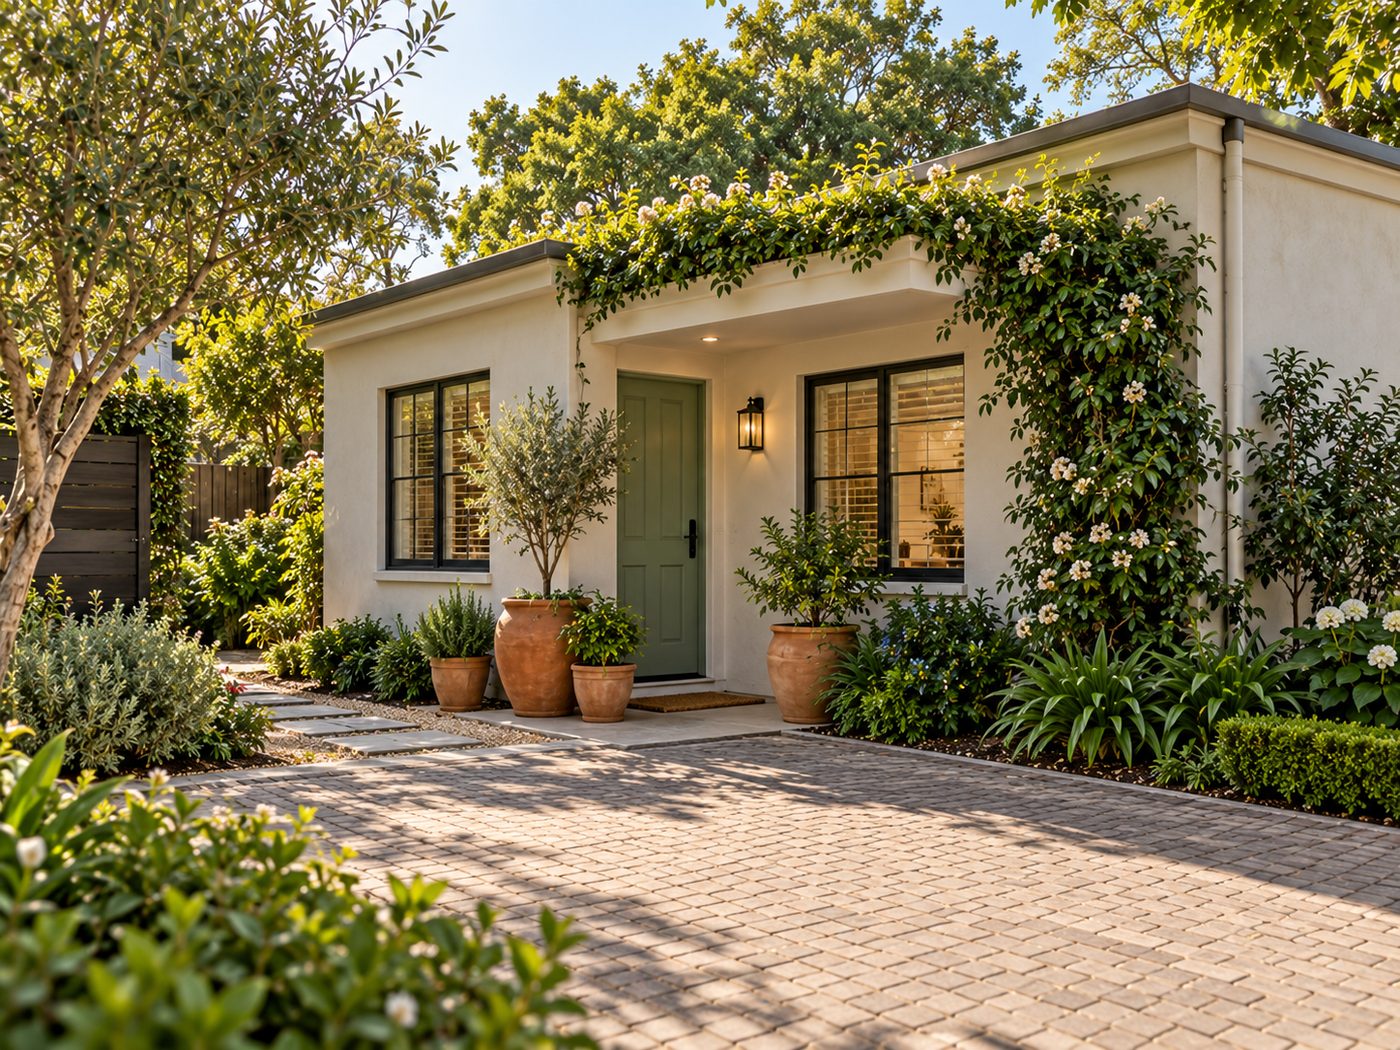 Cottage / Garden FlatAvailable Now
 TownhouseAvailable Now
Who we are
4Stone Properties lets and manages rental property for owners and investors across Brackenhurst, Brackendowns and Sandton.
Every home on this website is one we manage ourselves, so the person you phone has been through it and can answer your questions.
Inspired Service, Carved in Stone
Our Areas
Three suburbs, each close to schools, shops and main roads.

Larger stands and primary schools nearby. Mostly family homes.

A mix of family homes, secure complexes and flats, with easy access for commuters.

Apartments and secure complexes close to offices, malls and the Gautrain.
Why 4Stone
We list only homes we have been through ourselves, so what we say on the phone matches what you find at the door.
When a home is taken, it comes off this page the same day.
Call or WhatsApp the agent from any listing. The number goes straight to a phone.
Owners & Investors
We find the tenant, collect the rent and look after the property, with a monthly statement and a named person you can call.
Commercial
Offices, shops and light industrial units to let. Tell us the size and area you need and we will let you know when something suits.
Corporate
Furnished apartments, townhouses and houses leased in your company's name, with one lease and one monthly invoice, from a single flat to a whole team.
Tell us what you need and your budget, and we will get in touch when something suits.
Rentals
Rental homes in Brackenhurst, Brackendowns & Sandton
0 properties found
 HouseAvailable Now
 Cottage / Garden FlatFrom 1 November 2026
 HouseFrom 1 December 2026
 TownhouseAvailable Now
 ApartmentAvailable Now
 HouseFrom 15 November 2026TownhouseAvailable NowHouseFrom 1 December 2026Cottage / Garden FlatAvailable NowApartmentAvailable NowApartmentFrom 1 November 2026TownhouseFrom 1 January 2027
Rental specialists in Brackenhurst, Brackendowns & Sandton
4Stone Properties lets and manages homes for property owners and investors across Brackenhurst, Brackendowns and Sandton. Every home on this page is one we look after ourselves.
We take on only as many properties as we can manage properly, so each owner deals with a named person who knows their property. We would rather take a few extra weeks to find the right tenant than rush the wrong one in.
Own a rental property? See how we manage it for you.
When you call about a listing, you reach someone who has been through that exact property.
Meet the team
Call, WhatsApp or email us directly.
How we work
Enquiries answered the same day, viewings with an agent rather than a lockbox, and one number for anything that goes wrong.
Every home is one we have walked through ourselves, and repairs go to vetted contractors who are followed up until the job is done.
When something breaks, a burst geyser for instance, we send a contractor and follow up until it is fixed.
What to expect
Tell us what you need and your budget. If nothing on the list fits today, we will let you know as soon as something does.
We answer the same day, every day we are open
Fill in the form and your enquiry is emailed straight to our team. Fields marked * are required.
Owners & Investors
We find the tenant, collect the rent and look after the home, so you do not have to
What we take off your hands
Choose letting only, or hand us the whole job. Either way you deal with a named person who knows your property.
Photos, a clear listing and viewings held in person by an agent.
Read moreCredit, income, employment and previous-landlord checks, with the applicant’s consent.
Read moreRent tracked from the 1st, with follow-up the day a payment is late.
Read moreA monthly statement of every rand in and out, paid to you by a set date.
Read moreVetted contractors, your approval above a limit you set, followed up until done.
Read moreJoint ingoing and outgoing inspections with photos, plus a routine check during the lease.
Read moreFirm, lawful steps when rent stops, handled with your attorney.
Read moreGetting a home back to letting standard quickly between tenants.
Read moreDeposits held in an interest-bearing account and refunded the way the law requires.
Read moreHow it works
More for owners
Tell us where it is and when it will be free. We will come back to you with a rental estimate and what we would do.
Owners & Investors
Every rand accounted for, every month
You should never have to chase us for your money or wonder where it went. Rent comes in, approved costs go out, and the balance is paid to you with a statement that shows every line.
We send an annual summary of income and expenses for the tax year (March to February), which your accountant can use for your rental income tax return.
Rent and deposits are paid into a trust account, kept separate from our own business funds, as the Property Practitioners Act requires. See Legal Compliance for more.
Owners & Investors
The right tenant is the most important decision we make for you
Most rental problems start with the wrong tenant. We take the time to check every applicant properly, and you approve the final choice.
We assess every applicant on the same criteria. The Constitution and the Rental Housing Act prohibit unfair discrimination, including on race, gender, pregnancy, marital status, disability, religion or age, and we follow that strictly. Applicants’ personal information is handled under POPIA and kept only as long as we need it.
We send you a summary of the applicant we recommend and why. Nothing is signed until you are happy.
Owners & Investors
Firm, early and always within the law
Good screening keeps arrears rare. When rent is late, we act quickly, because the longer it runs the harder it is to recover.
A tenant can only be evicted from a home with a court order, under the Prevention of Illegal Eviction from and Unlawful Occupation of Land Act (the PIE Act). Changing the locks, removing belongings or cutting off water or electricity to force a tenant out is unlawful, and we never do it.
We work with your attorney through the process: preparing the lease, statements and correspondence they need, and keeping you informed at each step. Legal costs are for the owner’s account and are often recoverable from the tenant in terms of the lease.
Commercial leases are not covered by the PIE Act and follow a different, usually quicker, process.
Owners & Investors
Repairs handled properly, without surprises on your statement
Tenants report problems to us, not to you. We get the right contractor out, check the work, and only pay once the job is done.
As a rule, the owner pays for repairs from fair wear and tear and for the structure, roof, geyser and fixed installations. The tenant pays for damage they cause beyond normal use. The lease sets this out clearly so there is no argument later.
We use contractors we have worked with before, who quote first and invoice on completion. Certificates of compliance (electrical, gas, electric fence, beetle and plumbing where needed) are arranged when a property is sold or as the law requires.
Owners & Investors
A clear record of the property, from move-in to move-out
Inspections protect you and the tenant. They are the evidence that settles any question about damage and the deposit.
Before the tenant moves in, we inspect the property together with them and record its condition room by room, with dated photographs. Both parties sign the report. The Rental Housing Act requires a joint inspection like this.
We arrange a routine inspection during the lease, with reasonable notice to the tenant, and send you a short report with photos and anything that needs attention.
We inspect again with the tenant before they hand back the keys, within three days of the end of the lease. We compare it with the ingoing report and work out any damage beyond fair wear and tear. This decides what, if anything, comes off the deposit. See the Deposit Process.
Owners & Investors
The right tenant sees your home, quickly
An empty month costs you a month’s rent. Good marketing shortens it, and a fair asking price matters most of all.
We will tell you about anything that will put tenants off, from a dripping tap to a tired coat of paint. Small fixes often let a home sooner and for more. See Rent Ready.
Want to know what a slow let is costing? Try the Vacancy Loss Calculator.
Owners & Investors
Paid on time, followed up the same day it is not
Rent is due on the first of the month. We check every payment and contact the tenant the day one is missing.
We follow a set process of reminders, a letter of demand and, with your instruction, cancellation and legal action. Read Arrears & Evictions.
Owners & Investors
Back on the market quickly between tenants
The days between one tenant leaving and the next moving in are where most rental income is lost. We plan for them before the old lease ends.
Where possible we start marketing during the tenant’s notice period, with their co-operation for viewings, so the next lease starts soon after the last one ends.
Owners & Investors
Offices, shops and light industrial units, let and managed
Commercial property works differently from a home. Leases are longer, tenants are businesses, and the details matter more.
Larger businesses (an annual turnover or asset value of R2 million or more) are not protected by the Consumer Protection Act, and evictions from business premises do not fall under the PIE Act. Leases can run for longer and on terms the parties negotiate. VAT may apply to commercial rent if the owner is a VAT vendor.
Looking for space instead? See Commercial For Rent.
Owners & Investors
What you can hold us to
These are the standards we work to for every owner and every tenant. If we fall short, tell us and we will put it right.
One agent who knows your property and answers your calls.
Every message, from you or your tenant, answered promptly.
With an agent, when we said they would happen.
No repair above your limit without your say, and every cost shown on your statement with the invoice.
Rent paid over to you by the agreed date each month.
If you are not happy, our agreement lets you end it on reasonable notice. No lock-in.
These commitments describe how we work. The legal terms of our service are set out in the Management Agreement.
Owners & Investors
Straight answers to what owners ask us most
We look at what similar homes nearby have actually let for recently, then see the property in person. You will get a realistic figure, not an inflated one to win your business.
Yes. We screen applicants and recommend one, with our reasons. Nothing is signed without your approval.
Rent is due from tenants on the 1st. Your balance is paid by the date set in the agreement, with a statement. See Accounting & Statements.
We do, in an interest-bearing account as the Rental Housing Act requires. The interest belongs to the tenant. See the Deposit Process.
We act the same day and follow a set, lawful process. Read Arrears & Evictions. Many owners also take out rental guarantee or landlord insurance cover, which we can tell you about.
Above a limit you choose, yes. Below it we go ahead so small jobs are not held up, and every cost is shown on your statement.
Yes. The lease continues with the new owner (the principle known as “huur gaat voor koop”), and we can help with viewings while the tenant is in.
By giving written notice as set out in the Management Agreement. The tenant’s lease is not affected.
Yes. Net rental income is added to your taxable income. We send a yearly summary to help your accountant, but we do not give tax advice.
Owners & Investors
Clear packages, no hidden charges
Choose the level of help you want. Every fee is set out in writing before you sign anything.
Quoted per property
Quoted per property
Quoted per property
Fees are plus VAT where applicable. Costs such as repairs, certificates of compliance, legal fees and portal advertising are paid from the rent only with your approval and shown on your statement.
Owners & Investors
What you sign, in plain language
Our mandate is a short, plain-language agreement between you and us. We will take you through it before you sign, and you are welcome to show it to your attorney.
We are happy to send you our standard agreement to read before we meet. Request a copy.
Owners & Investors
Held properly, refunded fairly
The deposit is the tenant’s money, held as security. The Rental Housing Act sets out how it must be handled, and we follow it to the letter.
Only unpaid rent and the cost of repairing damage beyond fair wear and tear may be deducted. The balance is refunded within 14 days of the property being restored, with the receipts showing what was spent.
If the tenant does not attend the outgoing inspection, we inspect without them and refund any balance within 21 days of the end of the lease.
Disputes that cannot be settled between the parties can be referred to the Gauteng Rental Housing Tribunal, at no cost to either side.
Resources
The South African laws behind every lease we manage
Letting property in South Africa is governed by several Acts. This is a plain-language summary of the ones that matter most to owners and tenants, and how we apply them. It is general information, not legal advice.
Anyone who lets or manages property for others must be registered with the Property Practitioners Regulatory Authority (PPRA) and hold a valid Fidelity Fund Certificate. Rent and deposits must be kept in a trust account, separate from the agency’s own money.
You are entitled to see any agent’s Fidelity Fund Certificate. Ask us for ours.
The CPA applies to most residential leases where the landlord lets in the ordinary course of business.
No one may be evicted from their home without a court order. Locking a tenant out, removing their belongings or cutting off water or electricity to force them out is unlawful. Read how we handle arrears and evictions.
Applicants’ and tenants’ personal information, including ID numbers, payslips and credit reports, may be used only for the purpose it was given, must be kept secure and may not be kept longer than needed. Credit checks are run only with written consent. See our Privacy Notice.
Property practitioners are accountable institutions under FICA. That is why we ask owners and tenants for identity documents and proof of address, and why some transactions must be reported.
See how we put this into practice in Property Management.
The full text of each Act is published by the government at gov.za.
Resources
What a rental property really earns, before and after the bond, this year and in years to come
What you paid, or would pay, for the property.
The rent you expect to charge each month. Check what similar homes nearby let for.
Body corporate levies plus municipal rates and taxes. Use 0 for anything that does not apply.
Building (homeowner’s) insurance, plus landlord cover if you take it.
Money set aside for repairs. 5–10% of the rent is typical; more for older homes.
What an agent charges to manage the property, as a percentage of rent collected. Add VAT if it applies.
How long the property is likely to stand empty each year between tenants.
How much the rent goes up each year. South African leases usually escalate 5–8% a year.
How much levies, rates, insurance and upkeep rise each year. These often rise faster than rent.
Your deposit plus transfer duty, attorney fees and bond registration costs.
The yearly interest rate on your bond. Use the rate your bank offers you.
How many years the bond runs. 20 years is standard in South Africa.
A guide only, based on the figures you enter. It does not take the place of advice from your accountant or financial adviser.
Resources
Compare selling now with letting the property and selling later, after tax
What the property would sell for today.
The balance left on your home loan. Use 0 if it is paid off.
The yearly interest rate on your bond now.
What you pay the bank each month.
Agent’s commission (often 5–7.5% plus VAT), compliance certificates and bond cancellation costs.
Tax figures for the 2026/27 tax year.
The name the property is registered in. This changes how much of the gain is taxed, and at what rate.
Rental profit and gains paid out to beneficiaries in the same tax year are taxed in their hands, usually at a lower rate, instead of the trust’s flat 45%.
What was paid for the property, plus transfer costs and the cost of improvements (not repairs). The capital gain is the selling price less this.
The highest income tax rate you pay, between 18% and 45%. Used for capital gains tax and for tax on rental profit.
How long the property has been owned, up to today.
If it is your home, the first R3 million of the gain is free of capital gains tax. Once it is let, only the share of the gain from the years you lived there qualifies.
The rent you expect to get each month.
Levies, rates, insurance, maintenance and the management fee together.
How much rent and running costs rise each year.
How much you expect the property’s value to grow each year.
What you would earn each year on the sale money, for example in a unit trust or fixed deposit, after tax on that return.
How many years ahead to compare. Both options end with the property sold.
A guide only, based on the figures you enter. It does not take the place of advice from your accountant or financial adviser.
Resources
What an empty property is really costing you
The monthly rent the property lets for.
How long the property stands empty between tenants. A well-priced home usually lets within 2 to 6 weeks.
Bills you still pay with no tenant: levies, rates, basic water and electricity, security and garden service.
Once-off costs to get a new tenant in: cleaning, repairs, paint and the letting fee.
Resources
How much rent you can comfortably afford, and what you need to move in
Income before tax and deductions, for everyone who will sign the lease. Include regular commission or overtime, not once-off bonuses.
Car finance, personal loans, store cards and credit cards. Leave out the rent you pay now.
Most landlords ask for one to two months’ rent as a deposit, paid before you move in.
Any once-off lease, admin or credit-check fee. Ask the agent; use 0 if there is none.
A guide only. Landlords also look at your credit record and rental history.
How we handle your personal information under POPIA
4Stone Properties respects your privacy. This notice explains what personal information we collect through this website, why we collect it, how we use and protect it, and the rights you have under the Protection of Personal Information Act 4 of 2013 (POPIA).
4Stone Properties is the responsible party for the personal information collected on this website. We let and manage rental homes in Brackenhurst, Brackendowns and Sandton, Gauteng.
Our Information Officer is responsible for making sure we comply with POPIA and can be reached at info@4stoneproperties.net.
Information you give us. When you send an enquiry we collect your name, phone number, email address, the subject of your enquiry, the property you are interested in, your preferred agent and your message. If you call, WhatsApp or email us directly, we receive your number or address and what you send us.
Information collected automatically. Like most websites, our hosting provider records technical information such as your IP address, browser type and the pages you request, in server logs used for security and troubleshooting. To stop spam, the enquiry form keeps a scrambled (hashed) version of your IP address for one hour.
Cookies and third parties. This website does not set its own advertising or tracking cookies. Pages load fonts from Google, and listing pages show a Google map; Google may receive your IP address and set cookies under its own privacy policy.
Please do not send us special personal information (such as health, religion or criminal records), ID numbers or banking details through the website. We will ask for what we need, securely, if you go on to apply for a lease.
We use your information only for these purposes or a purpose closely related to them. We do not sell it, and we do not send you direct marketing unless you have separately agreed to receive it.
We process your information on these grounds under section 11 of POPIA:
You may withdraw your consent at any time by emailing info@4stoneproperties.net. Withdrawing consent does not affect processing that already took place lawfully, but we may then be unable to help with your enquiry.
Some of these providers (for example Google and Meta) may store information outside South Africa. Where that happens, we rely on them being bound by laws or agreements that give protection similar to POPIA, as section 72 requires.
We keep enquiry information for as long as we need it to deal with your enquiry, and for no longer than 12 months after our last contact with you, unless you become a tenant (lease records are kept for as long as the law requires) or you ask us to delete it sooner. Spam-protection data is deleted after one hour.
The website uses an encrypted (HTTPS) connection, enquiries go straight to our business mailbox rather than being stored on the website, and only our agents can access them. If we believe your personal information has been accessed without permission, we will notify you and the Information Regulator as POPIA requires.
Under POPIA you have the right to:
To use any of these rights, email info@4stoneproperties.net. We may ask you to confirm your identity first, and we will respond within 30 days. A copy of records may be subject to the fee prescribed under the Promotion of Access to Information Act (PAIA); we will tell you the fee before doing the work.
Our Information Officer
10 Moray Drive, Bryanston, Sandton, Gauteng, 2191
info@4stoneproperties.net
Woodmead North Office Park, 54 Maxwell Drive, Woodmead, Johannesburg, 2191
Complaints: POPIAComplaints@inforegulator.org.za
Enquiries: enquiries@inforegulator.org.za
Phone: 010 023 5200 · inforegulator.org.za
Please read this before relying on anything on this website
This website is published by 4Stone Properties. By using it you accept the terms below. If you do not agree with them, please do not rely on the website and contact us directly instead.
Everything on this website, including listings, descriptions, pictures and videos, is provided for general information. It is not legal, financial, tax or investment advice. Before you sign a lease or make any decision that relies on information here, we recommend that you get independent professional advice.
All homes are subject to availability and may be let, withdrawn or changed at any time without notice. Rentals, deposits, levies, utility arrangements, lease terms and other details are given in good faith but are not guaranteed. Errors and omissions excepted (E&OE). Sizes and descriptions are approximate. Please confirm every detail with us in writing and view the home in person before you apply.
Some pictures on this website are AI-generated illustrations and are not photographs of the listed home. They show the general style of a property only. Ask us for photographs of any home you are interested in, or arrange a viewing.
Nothing on this website is an offer to let a property. A lease only comes into effect once your application has been approved, any required credit and reference checks have been completed with your consent, and a written lease agreement has been signed by both parties, as set out in the Rental Housing Act 50 of 1999.
We take reasonable care to keep this website accurate, but we cannot guarantee that the information is complete, correct or current, and we have not independently verified all of it. Content reflects our understanding at the time it was published and may change without notice. We are not obliged to update it.
To the extent permitted by law, 4Stone Properties, its owners, employees and agents are not liable for any loss or damage, whether direct or indirect, that arises from using this website or relying on its content. Nothing in this disclaimer limits or excludes any right you have under the Consumer Protection Act 68 of 2008 or any other law that cannot lawfully be limited or excluded.
This website links to services we do not control, such as Google Maps for maps and directions and WhatsApp for messaging. We are not responsible for their content, availability or privacy practices, and a link does not mean we endorse them.
We handle personal information in line with the Protection of Personal Information Act 4 of 2013 (POPIA). Our Privacy Notice explains what we collect, why, and your rights.
The content, design, logo and pictures on this website belong to 4Stone Properties or are used with permission. You may view and share links to the website for personal use, but you may not copy, reproduce or distribute any part of it, in any form, without our prior written consent.
This disclaimer and your use of this website are governed by the laws of the Republic of South Africa.
The details below are published in line with section 43 of the Electronic Communications and Transactions Act 25 of 2002.
10 Moray Drive, Bryanston
Sandton, Gauteng, 2191
South Africa
Phone: 083 310 1190
Email: info@4stoneproperties.net
Website: www.4stoneproperties.net